Personal Finance Tips to Save More Money in 2026
Saving money is less about deprivation and more about design. When your everyday systems quietly favor saving, the balance grows without a constant battle of willpower. These personal finance tips focus on the practical, low-effort changes that add up to real money by the end of the year.
Whether you are recovering from a tight stretch or simply want more breathing room, the strategies below meet you where you are. No shame, no complicated spreadsheets, just a clear plan you can start using today.
Start by Finding Your Money Leaks
Before you can plug a leak, you have to see it. Most people underestimate their small, frequent purchases by a wide margin. A daily coffee, a few app subscriptions, and impulse snacks can quietly drain hundreds of dollars a month.
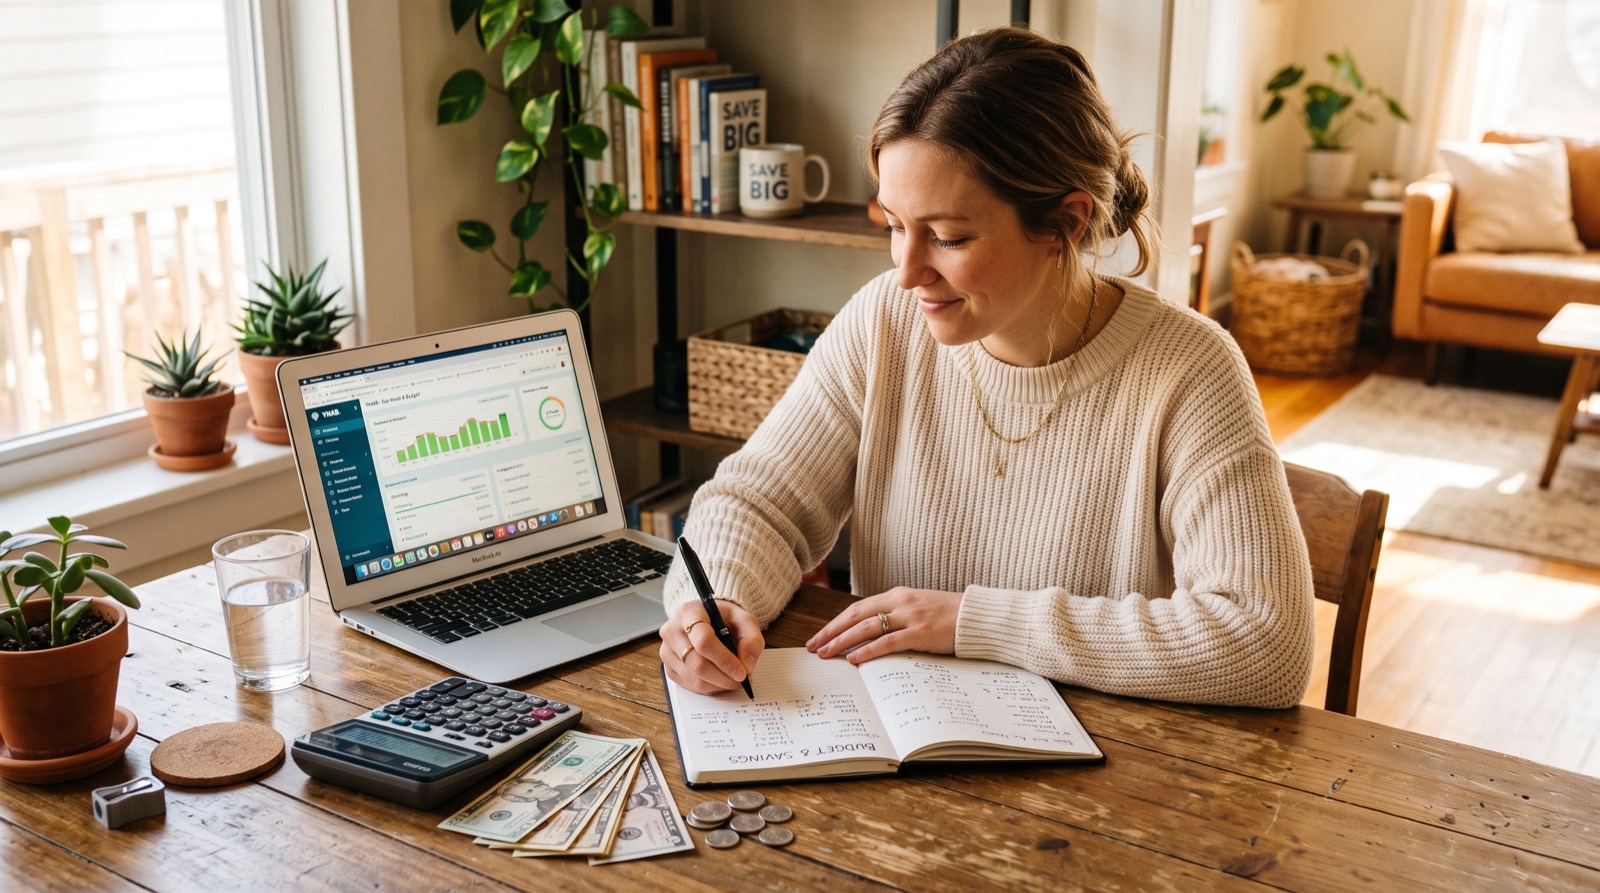
Spend one week writing down every purchase, or let an app do it for you. The goal is not guilt. It is a clear map of where your money actually goes versus where you think it goes.
The 24-Hour Rule for Impulse Buys
For any non-essential purchase over a set amount, wait a full day before buying. This simple pause cuts through the emotional pull of a sale and lets your rational brain decide. Most impulse wants fade within hours.
Automate Savings So You Never See the Money
The most reliable savers rarely rely on discipline. They rely on automation. When a portion of every paycheck moves to savings before you can touch it, saving becomes the default rather than the exception.
- Set an automatic transfer to savings for the day after payday.
- Split your direct deposit so a slice lands in a separate account.
- Use round-up features that sweep spare change into savings.
- Increase the amount by one percent every few months.
Pairing automation with the right tools makes it effortless. Modern money apps can schedule transfers, track goals, and celebrate milestones so the habit sticks.
Cut the Big Three: Housing, Transport, and Food
Trimming lattes helps, but the real leverage lives in your largest expenses. Housing, transportation, and food typically swallow the majority of a household budget, so even small percentage cuts here dwarf the savings from tiny sacrifices elsewhere.
| Expense | Quick win | Bigger move |
|---|---|---|
| Housing | Refinance or shop insurance | Take on a roommate or downsize |
| Transport | Combine trips and compare fuel prices | Go car-light or buy used |
| Food | Plan meals and shop with a list | Batch cook and cut delivery apps |
Energy costs deserve special attention in 2026. The U.S. Department of Energy notes that simple efficiency upgrades can meaningfully lower utility bills, and its Energy Saver guide lists changes that pay for themselves over time.
How Can You Save Money on a Low Income?
Saving on a tight budget is harder, but it is not impossible. The key is to protect small wins fiercely and stack every available advantage rather than waiting for a big raise.
- Save whatever you can, even five dollars a week, to build the habit first.
- Claim every tax credit and benefit you qualify for.
- Use cashback and rewards on purchases you would make anyway.
- Negotiate recurring bills such as phone, internet, and insurance annually.
Learning never stops paying off here. Following clear personal finance tips regularly helps you spot new savings opportunities before they slip past.
Build Sinking Funds for Predictable Expenses
Big irregular bills wreck budgets because they feel like surprises even when they are not. Holidays, car maintenance, and annual insurance premiums arrive on schedule every year, yet they still catch people off guard.
Divide and Conquer
Estimate each yearly expense, divide by twelve, and set that amount aside monthly in a dedicated sinking fund. When the bill lands, the money is already waiting, and no credit card gets involved.
For major purchases like a new appliance or a home energy system, plan even further ahead. Comparing options with dependable specialists ensures a large outlay actually lowers your costs over the long run instead of adding to them.
Turn Saving Into a Game
Motivation fades when saving feels like a chore, so make it fun. A no-spend weekend, a 52-week challenge, or a friendly savings competition with a friend keeps the momentum alive. Visible progress, such as a chart on the fridge, taps the same reward loop that makes games addictive.
Give Every Saved Dollar a Job
Saving without a purpose often ends in raiding the account for something impulsive. When each dollar has a clear destination, the temptation to dip in fades because spending it would mean robbing a goal you care about.
Split your savings into named buckets rather than one vague pile. A vacation fund, a car-repair fund, and a long-term investing fund each carry emotional weight that a single generic balance never will.
- Name each savings goal something specific and motivating.
- Assign a target amount and a rough deadline to every bucket.
- Automate a small transfer into each one every payday.
- Celebrate visibly when a bucket reaches its target.
Match Your Timeline to the Right Account
Short-term goals belong in a high-yield savings account where the money stays safe and accessible. Long-term goals, those five or more years away, can handle the ups and downs of a diversified investment account, where compounding does the heavy lifting over time.
Frequently Asked Questions
How much of my income should I save each month?
A common target is 20 percent of after-tax income, but any consistent amount beats none. If money is tight, start with five percent and raise it gradually as your budget allows.
What is the fastest way to start saving money?
Automate a transfer to a separate savings account on payday. Removing the money before you can spend it is the single most effective step, and it works even on modest incomes.
Should I save or pay off debt first?
Build a small starter cushion of a few hundred dollars, then focus on high-interest debt. Once that is cleared, redirect those payments toward a fuller emergency fund and long-term goals.
Do savings apps really help?
Yes, when used consistently. They automate transfers, visualize goals, and round up spare change, which removes the friction that causes most people to stop saving after a few weeks.
Conclusion: Design a Life That Saves for You
You do not need a bigger paycheck to save more. You need better systems. These personal finance tips work because they shift saving from a daily decision into an automatic background process that quietly builds your future.
Choose one strategy, set it up this week, and let it run. Ready to make 2026 your best money year yet? Explore practical guides and tools, then design the money system your future self will thank you for.